Quick Answer
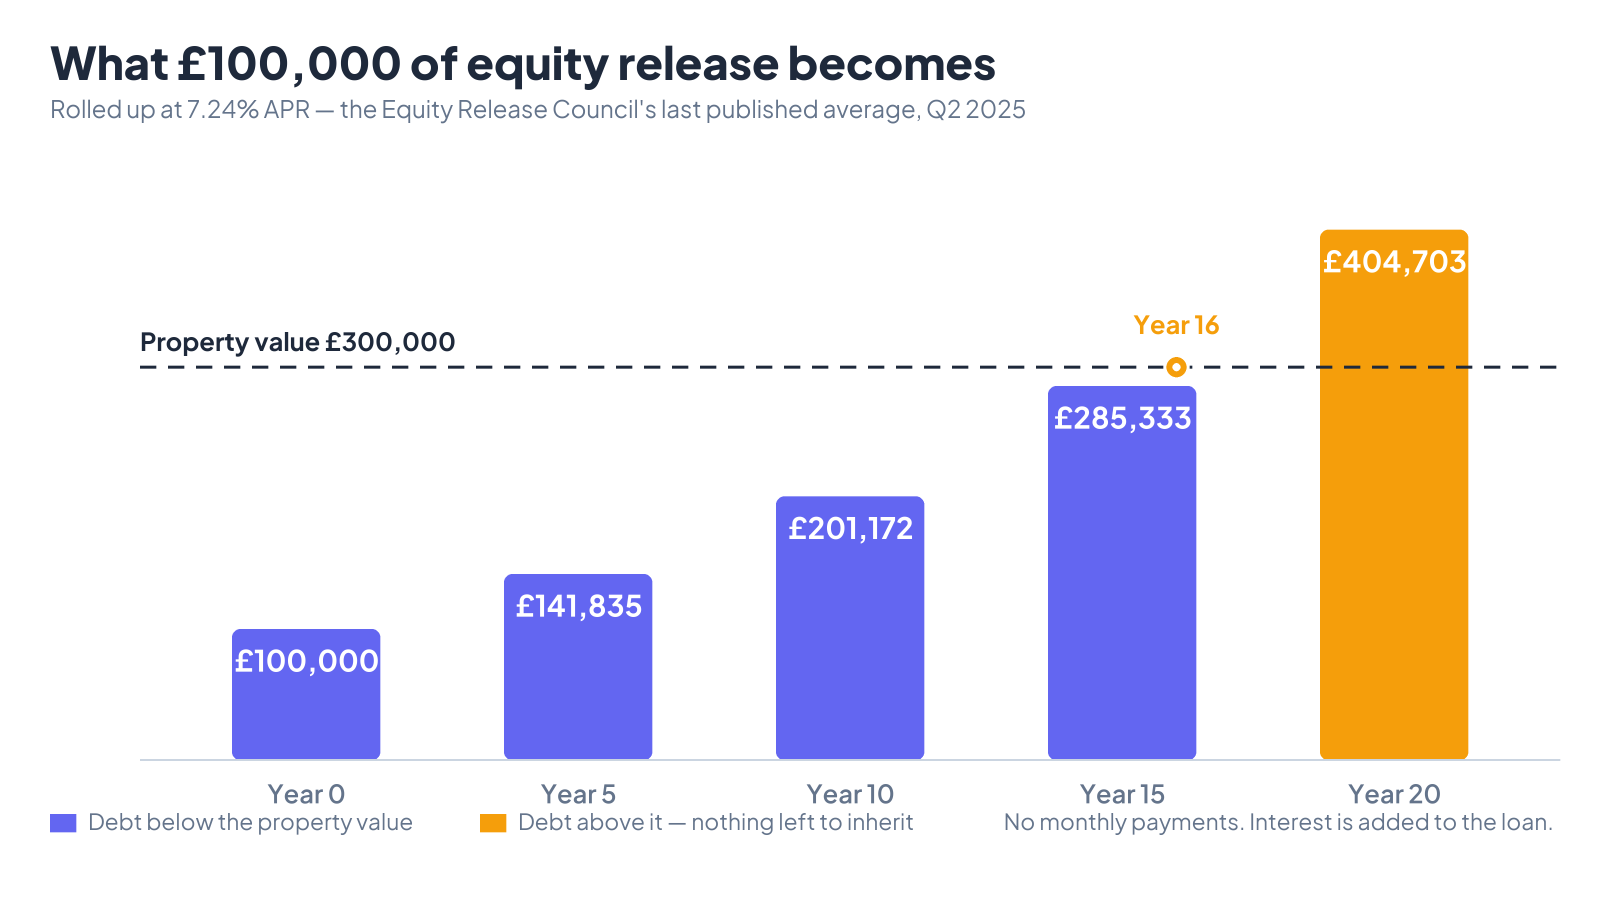
A lifetime mortgage rolls interest up instead of charging monthly payments, so the debt compounds. At 7.24% APR, £100,000 released grows to £285,333 after 15 years, 2.85 times the amount taken. Balance = amount × (1 + rate)^years. On a £300,000 home that leaves £14,667.
How Equity Release Roll-Up Interest Works
A lifetime mortgage pays you a lump sum secured on your home. You make no monthly payments. The interest is added to the loan each period and then earns interest itself, so the debt compounds for as long as the plan runs — usually until the property is sold, when you move into long-term care or after death.
That compounding is the whole story. MoneyHelper describes the mechanism plainly: in the first year the interest is based on the amount you borrow, that interest is added to the balance, and each following year the interest is calculated on the loan balance at the end of the previous year. The same page also refers to monthly roll-up, so check which basis your own agreement uses — the calculator above lets you switch between them.
Every plan that meets the Equity Release Council’s product standards carries a no-negative-equity guarantee. Its wording is specific: provided the property is sold for the best price reasonably obtainable and the loan terms have been met, “the borrower or estate will never owe more than the property is worth, after deduction of reasonable sales costs”. That caps what you can lose — it does not stop the debt reaching the value of the house.
The Roll-Up Formula
Two lines do all the work. The calculator uses the first by default:
Monthly roll-up: balance = amount × (1 + rate ÷ 12)12 × years
Equity left: property value − balance, floored at zero by the no-negative-equity guarantee
Nothing else is needed. Notice what the formula does not contain: no repayment term, because you make no repayments, and no amortisation, because nothing is being paid down. The multiple below is simply (1 + rate)years — how many times over the debt grows.
| Rate (APR) | After 10 years | After 15 years | After 20 years | After 25 years |
|---|---|---|---|---|
| 5.00% | 1.63× | 2.08× | 2.65× | 3.39× |
| 6.31% | 1.84× | 2.50× | 3.40× | 4.62× |
| 7.24% | 2.01× | 2.85× | 4.05× | 5.74× |
| 8.00% | 2.16× | 3.17× | 4.66× | 6.85× |
| 9.00% | 2.37× | 3.64× | 5.60× | 8.62× |
The Equity Release Council reported an average APR of 7.24% for Q2 2025, against 6.64% in Q2 2024 and a low of 6.31% in September 2024. Its Q1 2026 and Q2 2026 reports publish lending volumes but no rate at all, so 7.24% is the most recent published average and it is already dated. Use the rate on your own quote.
How Much Can You Release, and Why the Published Figures Disagree
There is no single published answer, and any calculator that gives you one is hiding something. Two sources publish figures, and they differ by roughly ten percentage points at every age where both appear.
Aviva publishes the only full age-by-age table available openly, in its product literature (document PF011139, dated 06/2023). It is one lender’s maximum, it is three years old, and Aviva states the figures may be altered “at any time and without notice”.
| Age | Aviva, single (06/2023) | Aviva, joint (06/2023) | Which? market typical (2026) |
|---|---|---|---|
| 55 | 15.5% | 12.5% | not published |
| 60 | 20.8% | — | not published |
| 65 | 25.6% | — | 35% to 39% |
| 70 | 30.4% | 27.4% | 40% to 44% |
| 75 | 34.5% | — | not published |
| 80 | 38.6% | — | not published |
| 85+ | 43.4% | 40.4% | not published |
Aviva publishes joint percentages for ages 55, 70 and 85+ only; the calculator interpolates between those three and says so on screen. Which? publishes a market-typical range for ages 65 and 70 only, and it is not extrapolated to other ages here, because two data points do not make a curve.
Treat the percentage as a starting point and overwrite it with the figure your own provider quotes. That is the only number that will actually apply to you.
How to Use the Calculator
-
Pick what you want to know
Use What will I owe? to project the debt forward, or How much could I release? to size the lump sum.
-
Enter the amount and the rate
Put in the lump sum you would take and the APR from your quote. If you do not have a quote yet, 7.24% is the Equity Release Council’s last published average.
-
Choose how many years
How long the plan is likely to run before the house is sold. Fifteen to twenty-five years is a common planning range.
-
Add your property value
Open Add your property value to see the equity left at the end. Leave growth at 0% for the cautious view — that is the one worth planning around.
-
Read the year-by-year table
It shows what the debt reaches at each milestone. A row turns red once the debt passes the property value, which is when the no-negative-equity guarantee starts doing the work.
Worked Examples
Every figure below is exactly what the calculator prints — enter the same inputs to check.
£100,000 released on a £300,000 house at 7.24%
| Years | Owed | Interest added | Multiple | Equity left |
|---|---|---|---|---|
| 10 | £201,172 | £101,172 | 2.01× | £98,828 |
| 15 | £285,333 | £185,333 | 2.85× | £14,667 |
| 20 | £404,703 | £304,703 | 4.05× | £0 |
| 25 | £574,011 | £474,011 | 5.74× | £0 |
Fifteen years in, the debt has nearly tripled and £14,667 of a £300,000 house remains. By year 20 the debt has passed the property value: the no-negative-equity guarantee means the estate owes no more than the sale proceeds, but there is nothing left to pass on. Adding 3% a year of house price growth changes the year-15 equity from £14,667 to £182,057 — which shows how much of the outcome rests on an assumption nobody can guarantee.
The year the debt passes the property value
| Rate (APR) | £100,000 released on a £300,000 house, no growth |
|---|---|
| 5.00% | Year 23 |
| 6.31% | Year 18 |
| 7.24% | Year 16 |
| 8.00% | Year 15 |
| 9.00% | Year 13 |
Under two percentage points of rate moves that crossover by ten years. When you compare quotes, this is the number the rate is really buying you.
Sizing the lump sum at 65
On a £300,000 property at age 65, Aviva’s published table gives 25.6%, or £76,800. Which? puts the market typical at 35% to 39%, or £105,000 to £117,000. Both appear in the calculator side by side, because the gap between them is larger than most people’s idea of a rounding error. If you still have a mortgage, it is repaid out of the release, so enter it and read the lower figure.
Equity Release Compared With Remortgaging to Release Equity
If you are under the minimum age, or you can service monthly payments, a remortgage or a further advance releases equity without the roll-up. You make repayments, the balance falls, and nothing compounds against you. The trade-off is that the payments have to be affordable on your retirement income, and the lender will test that.
Equity release removes the payment requirement entirely, and the cost of that is the compounding shown above. Our EMI calculator prices the monthly repayment on a conventional loan, which is the figure to weigh against the roll-up multiple before deciding.
Because a lifetime mortgage is repaid from the sale of the property, it comes out of the estate before anything is distributed. If you are weighing what would be left, our probate fees calculator works on the estate value after debts are settled.